
NEW YORK, UNITED STATES — September 04, 2026 (ACI Newswire) — The global home healthcare market is undergoing rapid expansion, driven by widespread demographic shifts, rising chronic disease prevalence, and a structural transition toward hospital-at-home care models. Industry data indicates the sector reached an estimated $485.3 billion in 2025. Projections suggest the market will surpass $1 trillion by 2033, expanding at a compound annual growth rate of 10.5%. This growth reflects a broader movement by healthcare systems to reduce inpatient admissions, lower costs, and improve patient comfort through remote monitoring and decentralized care.
Health system administrators and private insurers are increasingly aligned in their preference for home-based clinical services. Treating patients in their residences lowers the overhead costs associated with maintaining traditional hospital infrastructure. At the same time, patients recover in a familiar environment, which clinical studies frequently link to improved mental well-being and reduced hospital readmission rates.
Demographic Shifts and Chronic Disease Management Accelerate Growth
An aging global population remains the primary catalyst for the sustained demand in home healthcare services. According to demographic projections, the percentage of individuals aged 65 and older is steadily increasing worldwide. This age group experiences a higher incidence of age-related mobility issues and chronic conditions, including cardiovascular disease, diabetes, and respiratory disorders. Managing these conditions outside acute care facilities reduces the operational burden on hospitals while providing continuous, localized support.
Home healthcare operators are scaling their service offerings to meet this demographic reality. The services segment, which encompasses skilled nursing, physical therapy, nutritional support, and hospice care, currently accounts for more than 83% of total market revenue. Physicians increasingly prescribe post-acute care at home following hospital discharges for major surgeries, further embedding these services into standard treatment protocols.
Chronic disease management forms a large portion of daily home healthcare operations. For diabetic patients, regular monitoring and insulin administration can be managed entirely at home. Similarly, patients with chronic obstructive pulmonary disease (COPD) receive respiratory therapy and oxygen support without requiring frequent clinical visits.
Hospital-at-Home Models Ease Institutional Strain
Hospital capacity constraints have forced health systems to evaluate alternative care delivery methods. The hospital-at-home model provides acute-level care directly in a patient’s residence, utilizing mobile medical teams and advanced monitoring equipment. This approach mitigates overcrowding in hospital wards and drastically reduces the risk of hospital-acquired infections among vulnerable populations.
Administrators are adopting these programs to optimize resource allocation across their networks. By shifting lower-acuity care to the home, facilities can reserve inpatient beds for critical emergencies, intensive care needs, and complex surgical recoveries. Economic pressures also play a major role in this shift. Institutional care involves high fixed costs, whereas dispatching mobile nursing units and monitoring patients digitally offers a more flexible financial model.
Health insurance providers have recognized the cost-saving potential of these decentralized models. Many major payers now offer expanded coverage for home-based services that would previously require a prolonged hospital stay. This alignment of clinical and financial incentives is accelerating the implementation of hospital-at-home programs globally.
Technology and Telehealth Drive Service Expansion
Advancements in medical devices and digital health platforms serve as critical enablers of remote care delivery. The integration of connected diagnostics, wearable monitors, and telehealth software allows physicians to track patient vitals in real time. Medical device manufacturers are responding by developing sophisticated yet user-friendly equipment optimized for residential environments.
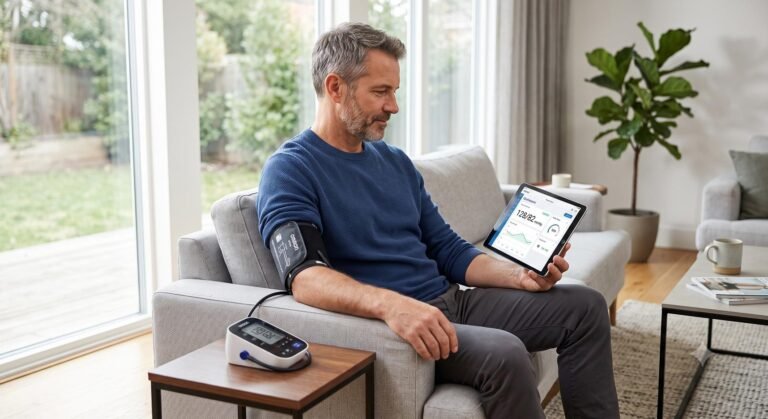
The equipment segment is witnessing rapid product development, specifically in therapeutic and diagnostic categories. Devices such as continuous glucose monitors, portable oxygen concentrators, and smart blood pressure cuffs are now standard tools for remote patient management. Additionally, at-home diagnostic testing for infectious diseases and routine blood work allows for faster clinical decision-making without a laboratory visit.
Telehealth infrastructure bridges the geographic gap between patients and specialized medical professionals. Video consultations and remote diagnosis platforms provide continuous clinical oversight without requiring physical travel. This connectivity is particularly beneficial for rural and underserved populations, where access to specialized medical facilities often remains severely limited.
Staffing Shortages and Reimbursement Complexities Remain
Despite robust demand, the home healthcare sector faces significant operational headwinds. A persistent shortage of qualified medical personnel, including registered nurses and home health aides, threatens to constrain market growth. Low compensation rates and demanding working conditions make recruitment and retention difficult across the industry. This supply-demand imbalance forces many agencies to limit their service capacity or reject new patient referrals entirely.
Reimbursement policies also present ongoing challenges for home health agencies. In the United States, recent adjustments to the Centers for Medicare & Medicaid Services (CMS) payment models place stricter emphasis on patient acuity and value-based outcomes. While these regulatory changes aim to improve care quality, they often reduce payment margins for smaller providers and rural healthcare networks.
The administrative process for securing durable medical equipment coverage remains complex. Providers frequently navigate stringent documentation requirements and authorization delays before delivering essential medical devices to a patient’s home. These bureaucratic hurdles can delay necessary treatments and increase the administrative overhead for home care organizations.
Regional Market Dynamics
North America continues to hold the largest share of the global home healthcare market, generating roughly 42.3% of total industry revenue. This dominance stems from established healthcare infrastructure, high per capita healthcare spending, and favorable government initiatives promoting home-based alternatives to institutional care. The presence of major corporate healthcare providers and a mature insurance market further solidifies the region’s leading position.
The Asia-Pacific region is projected to experience the fastest growth rate over the coming decade. Rapidly aging populations in Japan and China are driving substantial demand for remote monitoring and eldercare services. Concurrently, increasing healthcare investments and expanding private insurance coverage in India are facilitating the rapid adoption of home nursing and diagnostic services across urban centers. For instance, medical networks are committing substantial capital to regional expansion, with companies like Aster DM Healthcare announcing major investments to broaden operations across India.
European markets maintain steady growth, supported by robust public healthcare systems and strong regulatory frameworks. Countries like Germany and the United Kingdom are integrating digital health applications into their national health services, standardizing the reimbursement process for remote patient monitoring and home-based rehabilitation.
Industry Context
The broader implications of this market expansion extend beyond direct patient care into the financial and corporate sectors. Private equity firms and corporate healthcare entities are aggressively pursuing mergers and acquisitions within the home health sector to consolidate fragmented regional markets. This consolidation strategy aims to achieve economies of scale, integrate advanced data analytics into care coordination, and negotiate stronger reimbursement contracts with major insurance payers.
Major technology and retail corporations are also entering the home health ecosystem. These non-traditional healthcare entrants leverage their existing logistics networks and consumer platforms to deliver at-home diagnostics, prescription deliveries, and virtual care consultations. For example, Amazon India recently launched an at-home diagnostics service, offering rapid home sample collection and lab results within hours. This corporate activity underscores the sector’s financial viability and indicates a permanent shift toward consumer-driven healthcare models.
Key Facts and Figures
• The global home healthcare market was valued at approximately $485.3 billion in 2025.
• The sector is projected to expand at a compound annual growth rate of 10.5%, reaching $1.01 trillion by 2033.
• The services segment, which includes skilled nursing and therapeutic support, commands over 83% of the total market share.
• North America accounts for 42.3% of global market revenue, maintaining its position as the largest regional market.
• Demand for home medical diagnostic testing and mobility assist equipment continues to rise as acute care transitions to the home setting.
Neutral Conclusion
The home healthcare market is positioned for sustained structural growth over the next decade. Driven by demographic changes and technological integration, home-based care has evolved into a central component of global healthcare delivery. While labor shortages and evolving reimbursement frameworks will require careful strategic navigation by providers, the industry’s trajectory indicates a definitive shift toward decentralized, patient-centric treatment models. As governments and insurers continue to incentivize cost-effective care, home healthcare will play a crucial role in managing the clinical needs of an aging global population.
About ACI Newswire
ACI Newswire is a global provider of financial news, industry analysis, and corporate communications. Serving media organizations, institutional investors, and business professionals, ACI Newswire delivers timely market intelligence and editorial insights across major economic sectors. Our distribution network ensures comprehensive access to business developments driving the global economy.
Suggested Media Contact:
ACI Newswire
contact@acinewswire.com