
NEW YORK, UNITED STATES — September 15, 2026 (ACI Newswire) — The global financial technology sector generated approximately $650 billion in revenues in 2025, marking a 21% year-over-year expansion that materially outpaced traditional banking institutions. However, the industry has fundamentally shifted its strategic focus away from unchecked consumer acquisition. According to recent market analysis, 74% of the largest public fintech companies are now profitable, signaling an end to the era of expansion fueled primarily by cheap venture capital. Today, sustainable unit economics, horizontal software integration, and practical artificial intelligence applications are driving the sector’s maturation and reshaping the broader $15 trillion global financial services market.
Revenue Surges Amid Shifting Business Models
Despite prolonged macroeconomic headwinds and volatile interest rates, the fintech industry continues to capture market share from legacy financial institutions. Recent data indicates that the sector has expanded at an annual rate of 23% over the past four years, significantly outperforming traditional financial services, which grew by roughly 6% annually during the same period. North America remains the largest regional market, accounting for an estimated $310 billion in fintech revenues. This volume is predominantly supported by a mature consumer credit market, high credit card utilization, and robust loyalty programs that sustain transaction frequency. Payments continue to represent the largest vertical within the sector, contributing around $250 billion to the global total.
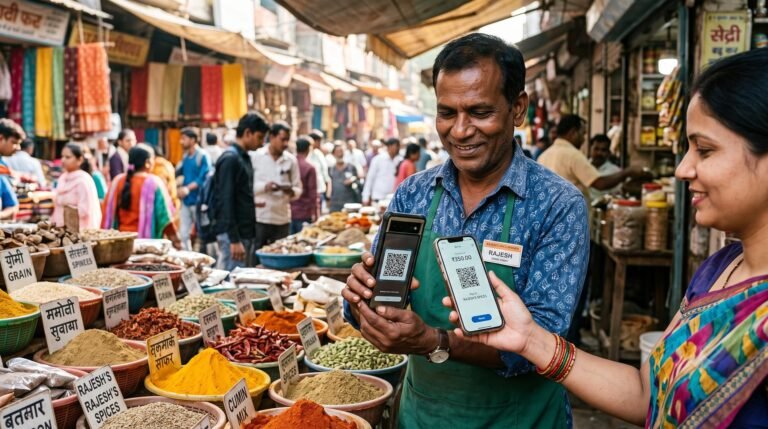
The most rapid expansion is occurring in emerging markets. Latin America has posted a 40% average annual growth rate over the last five years, largely driven by lending platforms that address significant gaps in consumer credit and rely heavily on installment payment structures. Similarly, the Asia-Pacific region is experiencing rapid adoption of account-to-account payments and digital wallets. These digital methods now facilitate roughly 30% of global point-of-sale transaction volume, led by frameworks like India’s Unified Payments Interface and Brazil’s Pix system. Meanwhile, Europe maintains a diversified revenue mix, balancing commercial net interest income linked to corporate treasury activity with robust consumer savings platforms.
Profitability Replaces Unchecked Expansion
For years, venture capital prioritized user acquisition and top-line revenue, often tolerating heavy operating losses to establish market dominance. The current financial environment demands a completely different approach. Industry analysts report that profitability is now a strict prerequisite for late-stage private funding and public market viability. Average earnings before interest, taxes, depreciation, and amortization (EBITDA) margins among the largest public fintechs increased by 400 basis points, reaching 20% in 2025.
This transition toward sustainable economics resulted from deliberate operational shifts. Management teams across the sector executed significant cost-reduction programs over the past two years, optimizing headcounts, shedding unprofitable business units, and raising pricing on core software-as-a-service products. Capital allocation has followed this trend closely. Total equity funding for the sector rebounded to $58 billion in recent data, representing a 53% year-over-year increase. However, investors are directing the majority of this capital toward mature companies with proven, positive unit economics. Early-stage funding remains restrained, resulting in a polarized investment landscape where late-stage winners access abundant capital while nascent startups struggle for liquidity.
Artificial Intelligence Redefines Operational Efficiency
Artificial intelligence is moving beyond experimental pilot programs and consumer-facing chatbots into core financial infrastructure. Leading fintech companies are embedding machine learning algorithms into essential back-office functions such as underwriting, fraud detection, and compliance monitoring. Firms implementing these technologies at a structural level report substantial operational advantages. Developer productivity at AI-forward fintechs has improved up to fivefold, allowing these companies to iterate on product features faster while maintaining lower overhead costs.
Furthermore, AI enhances risk assessment capabilities across global markets. Traditional credit scoring models often exclude large segments of the population due to rigid documentation requirements. Machine learning models, which analyze alternative data inputs including cash flow patterns and utility payments, enable fintech lenders to identify prime borrowers within historically marginalized demographics. A definitive divide is widening between companies deploying AI systematically across their operations and those utilizing it merely for isolated workflows or administrative assistance.
Incumbents Turn to Horizontal Software Providers
As consumer-facing neobanks diversify into comprehensive financial platforms offering lending, insurance, and wealth management, traditional banks face mounting competitive pressure. To modernize their legacy infrastructure without undertaking decade-long internal overhauls, these banks are increasingly partnering with “horizontal” fintechs. These software providers focus exclusively on digitizing incumbents from the inside out, improving the efficiency of the financial services value chain rather than competing directly for retail deposits.
Horizontal fintechs currently represent approximately 13% of total industry revenues but are growing 25% faster than their direct-to-consumer counterparts. By offering cloud-based core banking systems, application programming interface (API) payment gateways, and automated reconciliation tools, these enterprise providers allow traditional banks to deploy modern financial products rapidly. They are capturing significant value in B2B payments by investing in value-added services, including invoice automation and working capital optimization, particularly for small businesses and the healthcare sector. This dynamic shifts the industry narrative from pure disruption to collaborative modernization.
The Resurgence of Public Listings and Strategic Mergers
After a prolonged period of stagnant capital markets, liquidity events have returned to the financial technology sector. Initial public offerings rose significantly in 2025, with 31 new listings bringing the total market capitalization of publicly traded fintechs to a record $850 billion. Among the top 100 IPOs globally in 2025, fintech firms accounted for approximately 12% of total market capitalization, demonstrating renewed institutional confidence in the sector’s fundamentals.
Mergers and acquisitions are also accelerating at an unprecedented pace. Global transaction volumes jumped from $105 billion in 2023 to $251 billion in 2025. Notably, scaled fintechs outpaced traditional banks in acquisition activity for the first time on record, completing 659 deals compared to 589 by legacy institutions. These acquisitions are largely driven by a strategic need to acquire specific technical capabilities, such as digital asset infrastructure or advanced compliance systems. Because building these systems organically takes too long in a competitive environment, targeted acquisitions remain the preferred strategy for well-capitalized firms seeking to close technology gaps.
Digital Assets and Stablecoins Show Real-World Utility
The conversation surrounding digital assets is maturing, pivoting away from speculative token trading toward practical utility in global payments and treasury management. Stablecoins—cryptocurrencies pegged to fiat currencies—are gaining structural traction as a mechanism for cross-border settlements. Cash usage continues to decline globally, now accounting for just 46% of worldwide payments, pushing institutions toward digital alternatives.
While the reported annual transaction volume for stablecoins reached $35 trillion, analysis indicates that only about $390 billion represents actual end-user payments, such as supplier remittances or vendor disbursements. The remainder largely consists of trading and crypto-native arbitrage activities. Nevertheless, institutional interest remains high. Projections suggest the market value of stablecoins could expand to between $2 trillion and $4 trillion by 2030, representing a compound annual growth rate of nearly 40%. Traditional payment networks are increasingly exploring tokenized asset frameworks to reduce settlement times and lower the costs associated with international fund transfers.
Regulatory Compliance Becomes a Competitive Advantage
Regulatory scrutiny over financial technology firms has intensified across global jurisdictions. Rather than viewing compliance as a barrier to entry, industry leaders are leveraging it as a distinct competitive advantage. In the United States and the United Kingdom, major fintech companies are increasingly applying for federal bank charters. Securing a formal charter lowers funding costs, provides direct control over product architecture, and establishes direct ownership of the customer relationship.
This shift requires institutional-grade compliance frameworks, rigorous anti-money laundering controls, and capital reserve requirements that early-stage startups generally cannot afford. Consequently, companies with mature regulatory postures command higher valuations and investor trust. Trusted distribution networks—built through years of reliable operations, transparent consumer practices, and regulatory adherence—are becoming more critical than user interface design in determining long-term market winners.
Industry Context: A Maturing Global Market
Despite the impressive top-line revenue figures, fintech companies currently capture only about 4% of the total global financial services revenue pool. This metric highlights both the progress made over the last decade and the vast addressable market that remains untapped by digital challengers. Neobanking, while still a modest slice of the overall market, is projected to expand rapidly as consumer preference shifts decisively from branch-centric banking to mobile-first financial management.
The transition from a growth-at-all-costs mindset to sustainable profitability marks a definitive milestone for the sector. Traditional financial institutions are modernizing rapidly, often facilitated by the very technology firms they once viewed as existential threats. Real-time payment mandates in North America and open-banking API standardization in Europe are further accelerating this integration. At the same time, the largest fintechs are evolving into diversified financial platforms capable of servicing retail consumers, small businesses, and multinational corporations simultaneously.
Conclusion
The financial technology sector operates in a new equilibrium. Surpassing $650 billion in global revenue, the industry is no longer defined by speculative expansion but by measurable operational performance, strategic consolidation, and regulatory maturity. With a renewed focus on profitability, horizontal enterprise solutions, and pragmatic applications of machine learning, fintech firms are structurally integrating into the broader global economy. The current landscape confirms that future market leadership will depend less on customer acquisition subsidies and more on delivering durable, cost-effective financial infrastructure.
About ACI Newswire
ACI Newswire is a global distribution platform providing direct access to financial news, corporate announcements, and market analysis. Operating across major financial hubs, ACI Newswire connects public companies, private enterprises, and financial institutions with a broad network of journalists, investors, and industry stakeholders. The platform delivers timely, professional corporate communications to support market transparency and business reporting.
Media Contact:
ACI Newswire
contact@acinewswire.com