
NEW YORK, UNITED STATES — September 15, 2026 (ACI Newswire) — The global preventive healthcare technologies and services sector has reached an estimated $412.59 billion in 2026, driven by a systemic transition across major health networks toward early detection and value-based care. Faced with escalating operational costs and rapidly aging populations, clinical systems and insurers in North America, Europe, and the Asia-Pacific are aggressively reallocating capital. This financial shift targets biomarker diagnostics, remote patient monitoring, and predictive analytics designed to intercept chronic conditions before they require acute medical intervention. Market analysts project this structural realignment will sustain a compound annual growth rate (CAGR) of 12.45% through 2031.
The economic pressure to manage disease proactively is fundamentally altering the business model of modern medicine. Rather than generating revenue strictly through late-stage treatment volumes, healthcare providers are increasingly compensated based on patient health outcomes and disease prevention metrics. This financial restructuring incentivizes widespread investment in clinical-grade screening technologies, data-driven patient education initiatives, and automated health tracking.
The Financial Imperative of Early Intervention
Macroeconomic pressures on global health systems are forcing a rapid and mandatory adoption of preventive frameworks. The rising prevalence of lifestyle-induced conditions, including type 2 diabetes and metabolic syndrome, has strained public health budgets globally. Health economists consistently warn that treating advanced chronic diseases is fiscally unsustainable for both state-sponsored systems and private payers.
A recent sector analysis indicates that digital preventive platforms and proactive care strategies could reduce healthcare expenditures in the United States alone by up to $350 billion annually. Telemedicine platforms and remote monitoring services have significantly altered the cost structure of routine health maintenance. By routing initial health assessments through digital channels, clinical networks can manage larger patient populations with substantially reduced overhead.
Telehealth consultations dedicated to preventive care have lowered average visit costs by 40% to 60% compared to traditional in-person clinical settings. Consequently, telemedicine technologies currently capture nearly 31% of the total preventive healthcare technology market. This efficiency allows hospital administrators to reserve physical infrastructure for critical care and complex procedures, optimizing resource allocation across broader regional networks.
Value-Based Care Reshapes Provider Economics
The pivot toward preventive medicine is closely tied to the broader implementation of value-based care (VBC) models. Traditional fee-for-service frameworks compensate physicians based on the sheer quantity of tests and procedures performed, inadvertently disincentivizing early intervention. Under VBC structures, provider networks assume a level of financial risk regarding the long-term health of their assigned patient populations.
Accountable care organizations (ACOs) are increasingly common frameworks where groups of medical professionals voluntarily coordinate high-quality care. When an ACO succeeds in delivering excellent health outcomes while spending capital efficiently, the organization shares in the savings achieved for the public or private insurer. This structural shift guarantees that preventive metrics, such as annual wellness visits and routine mammographies, are strictly monitored by clinic administrators.
This shared responsibility model mandates that clinics prioritize routine screenings, vaccinations, and comprehensive lifestyle counseling. Healthcare providers remain the dominant end-users of preventive technologies, currently holding an estimated 45.1% market share. Financial incentives are directly tied to quality metrics, ensuring that clinical efficiency aligns strictly with long-term public health objectives.
Diagnostic Precision and Biomarker Applications
The methodology behind routine health assessments is transitioning from broad, generalized physical examinations toward highly targeted, molecular-level evaluations. Diagnostic services account for the largest share of the market at over 34%, sustained by clinical demand for objective, quantifiable patient data. Within this segment, genetic and biomarker testing is recording the fastest sustained growth rate, expanding at over 6% annually.
The emergence of liquid biopsy technology represents a significant advancement in preventive oncology screening. These non-invasive blood tests detect circulating tumor DNA shed by cancerous cells, allowing physicians to identify aggressive malignancies before traditional imaging can detect a solid tumor mass. Clinical laboratories are heavily investing in next-generation sequencing platforms to process these complex diagnostic panels efficiently at scale.
Automated laboratory analyzers handle the majority of these diagnostic workloads, maintaining a 38.9% share of the hardware market. As sequencing costs decline, clinical laboratories are frequently bundling genetic risk assessments with standard metabolic panels. This commercial strategy increases the accessibility of precision medicine for average consumers while driving higher diagnostic volumes for laboratory chains.
Cardiovascular and Oncology Screening Direct Capital
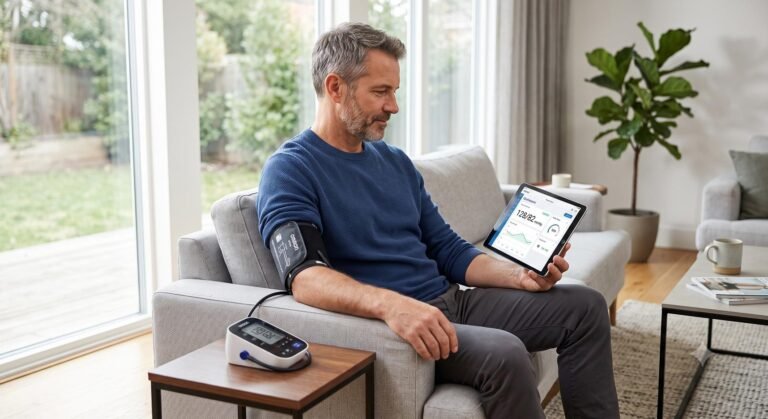
Chronic diseases represent the primary target for preventive capital expenditure across all major global markets. Cardiovascular disease prevention leads the market in application volume, capturing roughly 32.5% of total preventive revenue. Primary care networks routinely implement continuous blood pressure monitoring, comprehensive cholesterol screening, and digital heart health tracking for at-risk demographics.
Simultaneously, oncology screening applications are scaling rapidly as diagnostic hardware improves. Government-backed public health initiatives and specialized diagnostic centers are actively expanding cancer screening access to younger patient demographics. The clinical emphasis is moving toward identifying localized malignancies before they achieve systemic metastasis, which drastically improves survival rates and lowers overall treatment costs.
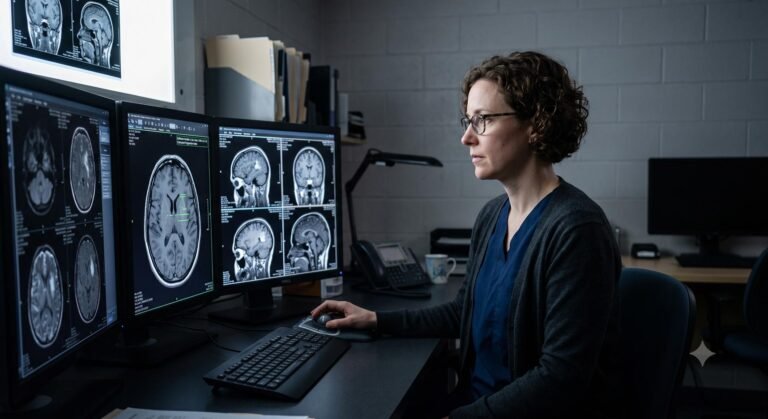
The integration of artificial intelligence in radiology and pathology allows health networks to process unprecedented volumes of screening data. Algorithmic image analysis helps clinical teams identify microscopic cellular anomalies that manual reviews might occasionally overlook. These automated triaging systems enhance diagnostic accuracy and reduce the administrative burden on specialized medical staff.
Telehealth and Remote Patient Monitoring Maturity
Consumer health tracking has transitioned from recreational fitness novelties to clinical-grade medical infrastructure. Wearable biometric sensors, including continuous glucose monitors and advanced electrocardiogram smartwatches, are now routinely integrated into electronic medical records (EMRs). This secure data integration provides physicians with continuous, real-time physiological metrics between annual physical checkups.
Continuous monitoring is particularly vital for managing metabolic disorders, diabetes, and hypertension in aging populations. However, market data indicates that the 31-to-45 age demographic dominates the utilization of these proactive health tools, capturing nearly 30% of market share. This metric illustrates a strong generational shift toward proactive health management early in adult life.
Younger patient cohorts demonstrate a high willingness to share continuous biometric data with primary care providers in exchange for personalized lifestyle counseling and targeted therapies. Hardware manufacturers are responding by developing discreet, non-invasive sensors that require minimal user interaction. These engineering improvements directly support long-term patient compliance and data accuracy.
Corporate Wellness and Insurance Payer Integration
Health insurance providers and corporate employers serve as major catalysts for preventive market expansion. Insurers are restructuring policy benefits to fully cover comprehensive screening packages, recognizing that early disease detection drastically reduces their long-term financial liabilities. Many large payer networks have eliminated patient copayments entirely for designated preventive visits and primary tier diagnostics.
Corporate wellness programs are evolving far beyond basic health risk assessments and subsidized gym memberships. Large multinational employers are partnering directly with regional diagnostic chains to offer employees on-site biomarker testing, ergonomic evaluations, and mental health screenings. These corporate initiatives aim to improve raw workforce productivity and reduce corporate health insurance premiums over a multi-year horizon.
In the active preventive health check-up segment, bundled clinical offers have proven highly effective in driving consumer adoption. Diagnostic chains frequently package complete blood counts, metabolic panels, and cardiovascular risk assessments into single, heavily subsidized service tiers. This commercial packaging simplifies the patient experience and generates consistent, recurring revenue for clinic operators.
Regional Adoption and Global Market Expansion
North America currently maintains the largest regional market share, accounting for 46.7% of global preventive medicine revenue. This dominance is supported by sophisticated digital health infrastructure, strong public awareness, and the presence of major pharmaceutical and diagnostic conglomerates. Early adoption of advanced clinical screening protocols continues to fortify the region’s market leadership.
Conversely, the Asia-Pacific region is registering the fastest economic growth within the preventive sector. Rapid urbanization, rising middle-class disposable incomes, and the increasing prevalence of lifestyle diseases are driving demand for private health check-ups across India, China, and Southeast Asia. Regional hospital networks are investing heavily in automated diagnostic laboratories and expanding their telemedicine outreach to rural populations.
European markets continue to demonstrate stable, steady growth, driven largely by state-sponsored universal healthcare systems. Governments across the European Union are standardizing population-wide screening programs for specific cancers and cardiovascular risks. These state directives ensure baseline preventive care access for their citizens while generating consistent demand for diagnostic equipment.
Regulatory Hurdles and Accessibility Challenges
Despite robust market expansion, the preventive healthcare sector faces substantial operational and regulatory barriers. Industry analysts caution that high initial technology implementation costs restrict smaller, independent clinics from adopting advanced diagnostic infrastructure. Analytics platforms and genomic sequencing equipment require significant capital investment and highly specialized clinical personnel.
Regulatory bodies, including the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA), are intensifying their oversight of digital health tools. Software as a Medical Device (SaMD) classifications require rigorous clinical validation before market approval can be granted. Manufacturers must prove that their predictive algorithms do not contain demographic biases, extending the time-to-market for new technologies.
Data privacy concerns present another major operational challenge for health networks. The constant transmission of sensitive biometric data between wearable devices, consumer applications, and hospital servers creates attractive targets for cyberattacks. Healthcare providers must continuously invest in enterprise-grade cybersecurity frameworks to maintain patient trust and comply with strict international data protection regulations.
The Future Trajectory of Proactive Medicine
The preventive healthcare market is fundamentally restructuring the modern clinical approach to human longevity and disease management. As the industry targets a valuation exceeding $741 billion by the early 2030s, the distinction between daily wellness management and formal medical treatment will continue to blur. The reliance on discrete, episodic clinical visits is steadily being replaced by continuous, data-driven health surveillance.
Addressing existing disparities in clinical access and digital reimbursement will require sustained cooperation between medical device manufacturers, clinical regulators, and insurance networks. Establishing standardized clinical guidelines for biomarker utilization and remote monitoring protocols remains essential for the next phase of market maturity. The long-term trajectory of the sector confirms that proactive disease management is rapidly establishing itself as the foundational standard of global medical care.
About ACI Newswire
ACI Newswire is a global corporate communications platform providing distribution services for financial disclosures, market research, and editorial business news. We facilitate the delivery of company announcements and industry analyses to media outlets, financial terminals, and professional data networks worldwide. ACI Newswire focuses on delivering clear, professionally formatted information to support corporate transparency and market awareness across diverse industry sectors.
Media Contact
ACI Newswire
contact@acinewswire.com