
LONDON, U.K. — September 22, 2026 (ACI Newswire) — Major manufacturing, retail, and technology sectors are increasingly adopting circular economy models, shifting away from traditional linear production methods. Driven by tightening international regulations and ongoing supply chain vulnerabilities, corporate boards are reevaluating how materials are sourced, utilized, and recovered. This structural transition, which emphasizes resource efficiency and waste reduction, has gained significant operational support across the electronics, textile, and packaging industries throughout the third quarter of 2026.
The movement toward circularity requires companies to design products for longevity, repairability, and eventual material recovery. Rather than the conventional “take, make, dispose” approach, businesses are investing in closed-loop systems. Industry analysts note that this shift is no longer viewed solely as an environmental initiative, but rather as a core risk management strategy designed to insulate companies from raw material shortages and volatile commodity prices.
Transitioning from Linear to Circular Operations
The integration of circular principles into corporate strategy involves comprehensive changes to product design and procurement. Manufacturing firms are now embedding end-of-life considerations directly into the initial research and development phases. By prioritizing modular designs and standardized components, these organizations make it financially viable to disassemble and recycle products once they reach the consumer limit.
Supply chain managers are simultaneously developing reverse logistics networks. These systems allow companies to efficiently collect used products from consumers, route them to refurbishment facilities, and reintroduce the materials into the manufacturing cycle. While the initial capital expenditure for reverse logistics is substantial, companies report that recovered materials often provide a more predictable cost baseline than virgin commodities.
Regulatory Frameworks Driving Global Compliance
Government mandates remain the primary catalyst for the widespread adoption of circular economy models. The European Union continues to lead this regulatory push through its Circular Economy Action Plan and the implementation of the Corporate Sustainability Reporting Directive (CSRD). These frameworks require large enterprises to disclose detailed data regarding their resource consumption and waste generation, forcing systemic operational audits.
In North America, momentum is building at the state and provincial levels. Extended Producer Responsibility (EPR) legislation is expanding, legally obligating manufacturers to fund the recycling and safe disposal of their products. These legal structures shift the financial burden of waste management from municipal governments back to the producers. Consequently, corporations are redesigning packaging and products to minimize their future liability under these EPR schemes.
Electronics and the Push for E-Waste Mitigation
The consumer electronics sector faces acute pressure to implement circular strategies due to the rising volume of electronic waste and the scarcity of critical minerals. Manufacturers are responding by increasing the use of recycled cobalt, lithium, and rare earth elements in new devices. This approach reduces dependence on environmentally intensive mining operations and secures material supply against geopolitical disruptions.
Simultaneously, the “right to repair” movement has influenced product architecture. Leading technology hardware firms are releasing repair manuals, supplying authorized parts to independent technicians, and designing devices with easily replaceable batteries and screens. By extending the operational life of hardware, companies reduce total e-waste volumes while generating new revenue streams through official parts distribution and certified refurbishment programs.
Packaging Coalitions and Material Redesign
Consumer packaged goods (CPG) companies are actively attempting to untangle their reliance on single-use plastics. Global coalitions, operating under agreements like the various regional Plastics Pacts, have committed to specific, time-bound targets for recycled content. Major beverage and food conglomerates are heavily investing in polyethylene terephthalate (PET) recycling infrastructure to ensure a steady supply of food-grade recycled plastics.
However, the transition is hindered by the limitations of mechanical recycling, which degrades plastic polymers over time. To address this, the industry is financing advanced chemical recycling facilities capable of breaking down mixed plastics into base monomers. Furthermore, brands are experimenting with alternative delivery models, including concentrated product formulations and reusable container programs, to fundamentally reduce the volume of packaging entering the market.
Textile Industry Faces Increased Accountability
The fashion and textile industry is undergoing a structural reassessment of its high-volume, low-durability business model. Regulatory bodies are targeting the sector’s intensive water usage and the proliferation of synthetic microfibers. In response, established apparel brands are launching internal resale platforms, allowing them to capture secondary market value from their own garments.
Material science investments are also focused on textile-to-textile recycling. Historically, blended fabrics like poly-cotton have been notoriously difficult to separate and recycle commercially. Recent advancements in automated sorting and chemical separation are providing the technical foundation needed to recover these fibers at scale. Brands are beginning to specify these recycled fibers in their procurement contracts to stimulate further investment in recycling infrastructure.
Investment Capital Flows Toward Circular Infrastructure
The financial sector has recognized the long-term viability of circular business models, directing private equity and venture capital toward resource recovery startups. Institutional investors are actively screening portfolios for circularity metrics, viewing heavy reliance on virgin materials as a long-term financial liability. Capital is specifically flowing toward artificial intelligence applications used in waste sorting facilities and logistics software designed to optimize reverse supply chains.
Green bonds and sustainability-linked loans are increasingly tied to circular performance indicators. Companies that successfully demonstrate a reduction in virgin material consumption or an increase in product recovery rates are accessing capital at more favorable interest rates. This financial alignment accelerates corporate commitment to circularity, as the cost of capital becomes directly intertwined with resource efficiency.
Supply Chain Security as a Primary Catalyst
Beyond regulatory compliance, the fragility of global supply chains has accelerated the transition toward circularity. Geopolitical tensions and localized trade restrictions have exposed the risks of relying on singular geographic regions for raw materials. By recovering materials domestically through robust recycling programs, manufacturing hubs can establish localized, secondary supply chains.
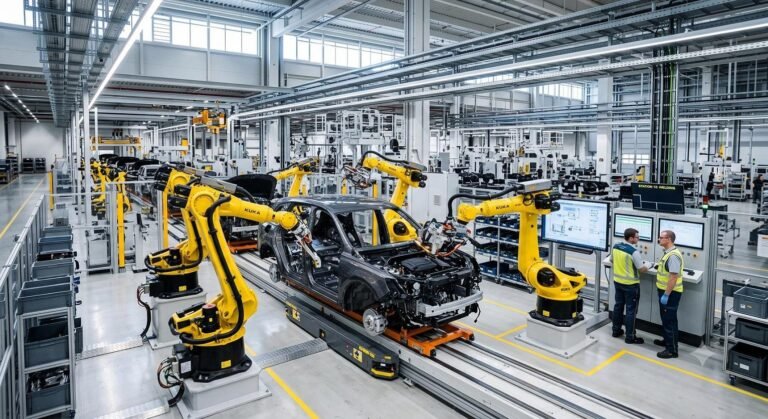
Automotive manufacturers, particularly those scaling electric vehicle (EV) production, are a prime example of this strategy. Automakers are partnering with battery recycling firms to extract lithium, nickel, and copper from spent EV batteries. Creating a closed-loop system for these critical metals is essential for the automotive sector to meet future production targets without exposing themselves to international commodity shocks.
Assessing the Long-Term Market Impact
The shift toward a circular economy represents a fundamental restructuring of industrial production rather than a temporary corporate initiative. While significant hurdles remain—including inadequate municipal recycling infrastructure and the current cost premium of certain recycled materials—the trajectory is firmly established by impending regulations.
Companies that delay adapting to these frameworks face the dual risk of restricted market access and escalating compliance costs. Conversely, organizations that successfully decouple their revenue growth from virgin resource consumption are positioning themselves for operational resilience. As international standards harmonize and recovery technologies mature, the circular economy is expected to become the baseline operating model for global manufacturing.
About ACI Newswire
\ACI Newswire is a digital distribution platform serving global business professionals, financial analysts, and the media. The platform syndicates corporate announcements, financial disclosures, and industry analysis across international markets. ACI Newswire focuses on delivering structured corporate communications and sectoral trends to targeted professional audiences, providing a direct channel for business reporting and market updates.
Media Contact
ACI Newswire
contact@acinewswire.com