
Digital Payments Continue Replacing Cash Transactions Globally, Driven by Mobile Adoption and Instant Settlement Networks
LONDON, UNITED KINGDOM — September 3, 2026 (ACI Newswire) – Digital payment methods now process the majority of global consumer transactions by value, fundamentally altering how money changes hands across both e-commerce and physical retail environments. Driven by surging mobile wallet adoption and government-backed instant payment networks, digital alternatives accounted for 66% of global online spending and 38% of in-store transaction value last year. While cash remains a necessary store of value and payment option for millions, its overall share of transaction volume continues to compress across developed and emerging economies alike.
The Mobile Device as a Financial Hub
Over the past decade, the smartphone has evolved into the primary conduit for consumer finance. This shift corresponds with unprecedented smartphone adoption worldwide. In 2007, global consumers purchased 122 million smartphone units; by 2024, active devices had risen to over 4.2 billion, with projections reaching 6.1 billion by 2029. Between 2014 and 2024, mobile devices’ share of global e-commerce payment volume tripled, rising from 19% to 57%.
At physical retail locations, digital payment volumes processed at the point of sale expanded from $1.2 trillion in 2014 to $14.2 trillion. Consumers increasingly favor the consolidated utility of digital wallets over carrying physical cards and currency. Noting this behavioral shift, Pinar Koygun, Senior Director for Retail at Worldpay, stated, “Left your cards at home? You have them all in your digital wallet. Convenience really is the reigning retail king”. Forecasters estimate that by 2030, mobile devices will facilitate 53% of all in-person shopping value, representing an estimated $25 trillion in consumer spending.
Instant Payment Networks Accelerate the Transition
The displacement of cash moves fastest in regions implementing government-backed instant payment infrastructure. These networks combine payment authorization and settlement into a single, real-time process, lowering merchant costs and increasing transaction velocity. They allow funds to transfer in seconds rather than days, encouraging rapid consumer adoption.
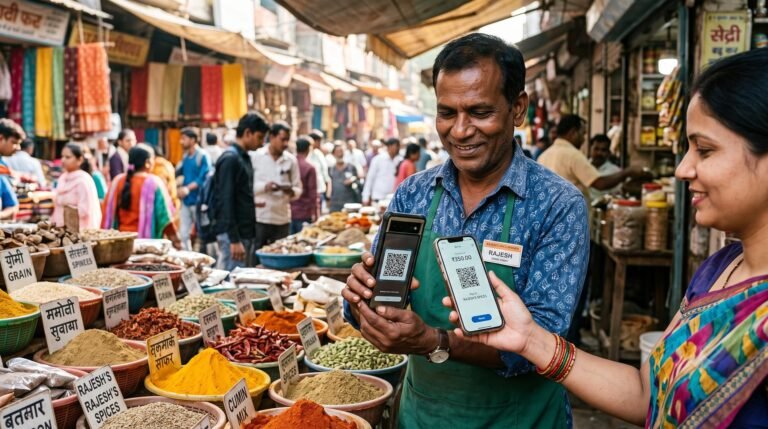
India’s Unified Payments Interface (UPI) provides the clearest example of this transition. When the system launched in 2016, cash represented 78% of the nation’s point-of-sale transaction value. By 2024, cash usage had fallen to 15%, while UPI managed 58% of physical retail and 64% of e-commerce transaction value.
A similar trend emerged in Brazil following the November 2020 launch of the Pix system. Within five years of operation, cash’s share of point-of-sale value in Brazil dropped by half, falling from 35% to 17%. Across Europe, account-to-account transfers through various instant payment frameworks now represent 17% of e-commerce value and 4% of physical retail value.
United States Payment Trends Show Stable Cash Floor
Despite the rapid ascent of mobile and electronic alternatives, physical currency maintains a consistent footprint in the United States economy. According to the Federal Reserve’s 2025 Diary of Consumer Payment Choice, cash accounted for 14% of all consumer payments by volume in 2024. It holds steady as the third most utilized payment method behind credit cards, which capture 35%, and debit cards at 30%. Furthermore, automated clearing house (ACH) transfers accounted for 11% of consumer payments.
American consumers average seven cash transactions per month, a figure that has remained unchanged since 2020. While digital wallet adoption expands, with 69% of U.S. adults reporting usage within a 30-day window, paper currency remains an essential fallback mechanism. Federal Reserve data indicates that more than 90% of U.S. consumers intend to continue using cash as either a payment method or a store of value.
The reliance on cash is particularly acute among financially marginalized populations. While the U.S. unbanked rate fell to 4.2% in 2023, 66.2% of unbanked households rely solely on cash for their transactions. For these demographics, physical currency serves as the primary tool for economic participation, underscoring the risk of financial exclusion in an entirely cashless ecosystem.
European Consumers Balance Digital Preference with Cash Access
In the euro area, the transition toward electronic payments proceeds steadily, though physical currency retains a majority share of total transaction volume. The European Central Bank’s SPACE 2024 study found that cash was used for 52% of all point-of-sale transactions, down from 59% in 2022. However, when measured by transaction value, card payments outpaced physical currency, holding a 45% share compared to cash’s 39%. For larger payments over €50, cards remain the most frequently used method.
Consumer preference data reveals a divergence between stated payment habits and actual usage. While 55% of euro area consumers prefer to use cards or cashless methods in physical stores, 62% consider it important or very important to maintain cash as an available option. Privacy concerns contribute to this dynamic, as 58% of respondents expressed unease regarding the privacy of their digital transactions or banking activities. Consequently, cash remains the dominant method for person-to-person transfers in Europe, accounting for 41% of those exchanges.
Access to physical currency also remains a priority for European banking regulators. Most euro area consumers reported satisfaction with their access to cash, though this satisfaction has decreased slightly in recent years. A large majority, 87%, find it fairly easy or very easy to access an ATM or a bank branch. Additionally, 57% of euro area consumers reported having the option to withdraw cash at shop counters, ensuring liquidity remains available in local communities without relying strictly on banking infrastructure.
Industry Context and Broader Market Impact
The ongoing migration toward digital infrastructure carries substantial implications for the global financial ecosystem. For merchants and financial institutions, the projected rise of digital payments—expected to capture 79% of e-commerce value by 2030—necessitates continuous investment in secure, multi-channel payment gateways. Retailers must adapt point-of-sale hardware to accommodate a fragmented landscape of mobile wallets, contactless cards, and QR-based instant payments.
However, the enduring demand for cash creates a structural challenge for policymakers and retail banks. Maintaining the infrastructure required to distribute, secure, and process physical currency becomes increasingly expensive as overall cash volumes decline. Central banks face the dual mandate of fostering innovation in digital payment systems while ensuring that cash remains universally accessible for populations that rely on it.
Looking Ahead
The payments landscape will likely continue its structural shift toward mobile and account-to-account frameworks. As proprietary digital wallets and sovereign instant payment networks mature, they will capture an increasing share of routine consumer spending. Simultaneously, cash will transition from the default medium of exchange into a specialized tool valued primarily for its privacy, immediate settlement, and universal accessibility.
About ACI Newswire
ACI Newswire is a global corporate communications platform providing editorial publishing and distribution services for financial institutions, enterprise organizations, and market analysts. We distribute primary business announcements, earnings reports, and economic data directly to newsrooms, financial terminals, and syndication networks worldwide.
Media Contact:
ACI Newswire
contact@acinewswire.com